The lessees balance sheet must show a right-of-use asset and a lease liability initially recorded at the present value of the lease payments (plus other payments, including variable lease payments and amounts probable of being owed by the lessee under residual value guarantees). WebFinance lease is a type of long-term financing where the company enters the lease agreement to use the property or asset for a long period of time. Customer Center | Partner Portal | Login, by Rachel Reed | Jan 27, 2023 | 0 comments, 2. 12/14/2022. 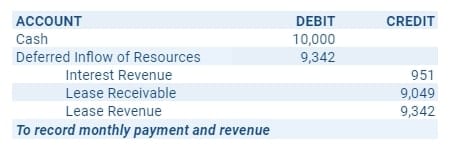 On January 31, 2021, ABC Company would record a journal entry to capture the accretion of the lease liability (i.e., remeasure the present value of future payments), amortize the right-of-use asset, and record lease expense. The equipment has a useful life of eight years and has no residual value. Under ASC 842 the same measurement principle applies under ASC 842. Contact +1 (888) 738-8030 [emailprotected], Head Office Depreciation is a tax-deductible expense, which is recognized by both the lessor and lessee. Thus, under the new standard, a lease is a finance lease if any of the following conditions is met at inception: In addition, the new standard does not permit the lessee to exclude a guarantee of residual value from the lease payments by obtaining an insurance policy for the benefit of the lessor. The present value of the sum of lease payments and any residual value guaranteed by the lessee not already reflected in lease payments equals or exceeds substantially all of the fair value of the underlying asset. WebSee in EZLease For this lease, the journal entries for month #2s rent payment would be: Each month, the rent payment is booked in the manner shown above, depreciation and interest are accrued and expensed, and liability is reclassified from long-term to current. The lease term is 3 years while the remaining useful life of the forklift is 5 years. 2. WebThe asset cost Robert $52,000. 140 Yonge St. This may include options to renew the lease if the lessee intends on exercising those options. Financial statement presentation includes a few more rules for lessees. This lessee has chosen to utilize the 90% threshold to represent substantially all of the fair value of the asset. Understand common leasing terms used on lease contracts Input of Lease data into LeaseQuery (Lease Software) Assist with the review of inputted lease data in LeaseQuery from other Subsidiaries Prepare or assist In this examples modification, its the future lease payments that have been modified. Under ASC 842, the lessee no longer recognizes a capital lease asset and capital lease obligation but a right of use asset and a lease liability. Criteria 5: Is the underlying asset of such a specialized nature it is expected to have no alternative use to the lessor at the end of the lease term? For a finance lease, the lessee debits the fixed asset account by the present value of the minimum lease payments. Criteria 2: Does the lease contain a purchase option the lessee is reasonably certain to exercise? Cradle Inc. Each annual payment of $127, 500 is due on December 31 . To ensure your lease liability has been calculated correctly ensure it unwinds to zero as shown in the below animation: Given there have been no other inputs to impact the value of the right of use asset. For both finance and long-term operating leases, disclosure of non-cash investing and financing activities is consistent with current guidance when obtaining a right-of-use asset in exchange for a lease liability. These requirements are demonstrated inExhibit 5. In that case, we have extensive material here to help determine the lease classification. The following journal entry represents the entry for amortization expense, which will not change throughout the lease: Journal entries in subsequent months will be similar to the first months entries. When doing journal entries, we must always consider four factors: Which accounts are affected by the transaction. Changing lease accounting to reflect the economic reality of lease obligations on lessees financial statements meant overcoming the vested interests of powerful interest groups. Calculation of ROU asset amortization expense for operating leases document.write('<'+'div id="placement_456219_'+plc456219+'">'); WebThis video shows how the lessee would account for a lease classified as a finance lease under the new lease accounting rule. XYZ Ltd. charges a total of $1,500 in the lease transaction. With Example 2, the lease liability amount before modification was $19,885.48. Download our free present value calculator to perform the calculation. The SEC report suggested that FASB undertake a project to revise lease accounting standards, further stating that the project would be more effective if it were a joint effort with the IASB. For an operating lease as all cash outflows are classified as "operating" in the statement of cash flows. If you would like greater detail on the concept of present valuing and the different options available, refer here. With implementation of the new standard, journal entries will change. Toronto, ON M5C 1X6 When tallying figures for the balance sheet, the lease liability and ROU asset accounts are now included. WebHere are the sample finance lease journal entries, first month: Easy testing. The formulas input do not change row by row. Is the implicit rate or incremental borrowing rate used for finance leases. If you are unsure if the lease is a partial termination, there is more information here and some practical examples of re-measure the lease liability and right of use asset. There is no bargain purchase option because the equipment will revert to the lessor. Resources On January 1, 2022, Company XYZ signed an eight-year lease agreement for equipment. The residual value is guaranteed to the lessor of $50,000 at the end of the lease term. As a result, the total expense for year one would be 1,175,000 dollars, which is made up of: 195,000 dollars of interest expense plus 980,000 dollars of amortization expense of the right-of-use asset. WebStep 1 - Work out the modified future lease payments Step 2 - Determine the appropriate discount rate and re-calculate the lease liability Step 3 - Capture the modification movement and apply that to the ROU asset value Step 4 - Update the right of use asset amortization rate Open site navigation How to Calculate a Finance Lease under ASC 842 To identify the characteristics that distinguished a capital lease from an operating lease, SFAS 13 established four criteria: If any single criterion was met, a lease was deemed to be a capital lease for the lessee, requiring the leased asset and the related lease liability to be listed on the balance sheet. The specific thresholds or bright linesfor the third and fourth tests have been removed under ASC 842. Under US GAAP, alessee records the leased asset for a finance lease as if they purchased it with funding provided by the lessor. The two standards differ on some points, but each accomplishes the joint objective of recognizing that leases give rise to assets and liabilities that should appear on the balance sheets of lessees. This includes rental income, expenses, and any other financial transactions that affect your business. var div = divs[divs.length-1]; Cash payments for costs incurred to put the leased asset in a condition and location required for its intended purpose and use should appear in the investing activities section. (Note: This company has maintained the greater than or equal to 75% threshold for this test). (Note: This company has maintained the greater than or equal to 90% threshold for this test). Specific modifications will result in a new lease. In this article, we'll walk through the initial journal entries for both lease classifications, Finance and Operating at the time of transition. The addition of $3,996.11 results in the right of use asset value post modification of $28,546.45 ($24,550.34+$3,996.11) at 2021-10-16 before amortization. Discovery of a solution did not take long: Changing lease accounting to reflect the economic reality of lease obligations on lessees financial statements meant overcoming the vested interests of powerful interest groups. At least one of the following conditions must be met in order to classify a lease as a financing lease: : The ownership of the right-of-use asset transfers from the lessor to the lessee by the end of the lease period. The following is the lease amortization schedule, prepared with the effective interest method, used to record the journal entries under finance lease accounting (rounded to the nearest whole dollar): We now have all the information we need to record the initial journal entry. A fter a nearly 10-year collaboration to develop a converged standard on leasing, on Jan. 13, 2016, the IASB issued IFRS 16,Leases,and on Feb. 25, 2016, FASB issued Accounting Standards Update (ASU) 2016-02,LeasesTopic 842. This figure is the closing balance at 2021-10-15 or the opening balance of 2021-10-16. The capital lease criteria under ASC 840 consisted of four tests to determine whether a lease was a capital lease or an operating lease. The visual below shows the journal entry for a lease that has a net present value of future minimum lease payments of $60,000. var divs = document.querySelectorAll(".plc461033:not([id])"); var AdButler = AdButler || {}; AdButler.ads = AdButler.ads || []; The calculation is then 116,375 / 365 = $318.84. From a calculation perspective, you also need to remember to update the calculation to use the latest discount rate in the XNPV formula and the calculation of interest earned on the lease liability. Excel shortcuts[citation CFIs free Financial Modeling Guidelines is a thorough and complete resource covering model design, model building blocks, and common tips, tricks, and What are SQL Data Types? Accounting for finance leases is generally consistent with the current guidance for capital leases. Exhibit 2illustrates an operating lease, including the calculations, amortization table, and required journal entries. WebIn this session, I discuss avvounting for a finance lease from a lessee's perspective including example and journal entries. If you want in-depth analysis, refer to our guide, which covers how the lease liability is measured and how the right of use asset's value is determined. EYs study concluded that spreadsheets were so prevalent because most companies had operating leases, which were off the balance sheet, and saw little need to develop more sophisticated systems to track them. In contrast to ASC 840, under ASC 842, the existence of a purchase option does not automatically classify a lease arrangement as a finance lease. The entries in Exhibit 4 illustrate how the lessee accounts for a finance lease given initial direct costs and residual value (guaranteed and unguaranteed). Rather, they are presented in the same manner as the entity presents all other interest and depreciation expenses on similar assets. It is worth noting, however, that under IFRS, all leases are regarded as finance-type leases. Assuming that the lease is classified as a finance lease, record Olympia's journal entry(s) on Recognize a right-of-use asset and a lease liability, initially measured at the present value of the lease payments, in the statement of financial position, 2. In the operating lease scenario, the lease expense is constant throughout the lease term. The only difference is lease classification. The discount rate is the lessors implicit rate or, if not determinable, the lessees incremental borrowing rate for a similar collateralized loan in a similar economic environment. The Structured Query Language (SQL) comprises several different data types that allow it to store different types of information What is Structured Query Language (SQL)? All rights reserved. The discount rate input into the calculation is one of the most subjective areas when calculating the lease liability. The most significant change is there are now five tests that determine lease classification instead of four. In our experience, most LeaseQuery clients have chosen to keep the existing thresholds of 75% and 90%, respectively, for continuity purposes. The debit must go somewhere. It is worth noting, however, that under, This step-by-step guide covers the basics of lease accounting according to IFRS and, Whether the risks and rewards have been fully transferred can be unclear, so IFRS outlines several criteria to. Sign up now ARO Criteria 3: Is the lease term greater than or equal to the major part of the remaining useful life of the asset? Instead, the criteria is focused on the lessees determination (using economic factors) of its likelihood to exercise a purchase option within the agreement. Year 0 is considered the current year, 2022. }, PricingASC 842 SoftwareIFRS 16 SoftwareGASB 87 SoftwareGASB 96 Software, Why LeaseQuery New York, NY 10005 In Excel, we can calculate the PV of the minimum lease payments: type = 1 (payment is made at the beginning of the year), calculate PV as =PV(10.5%,8,28500,0,1) = $164,995, 164,995/166,000 = 99% (refer to the present value condition above), =PV(10.5%,8,-28500) the negative figure shows that this is a cash outflow, =NPV(10.5%, E3:E10) the lease payments shown in the table above are in the range E3:E10, You can read more about lease accounting on the. AdButler.ads.push({handler: function(opt){ AdButler.register(165519, 459496, [300,600], 'placement_459496_'+opt.place, opt); }, opt: { place: plc459496++, keywords: abkw, domain: 'servedbyadbutler.com', click:'CLICK_MACRO_PLACEHOLDER' }}); document.write('